How to measure AI ROI: the direct answer
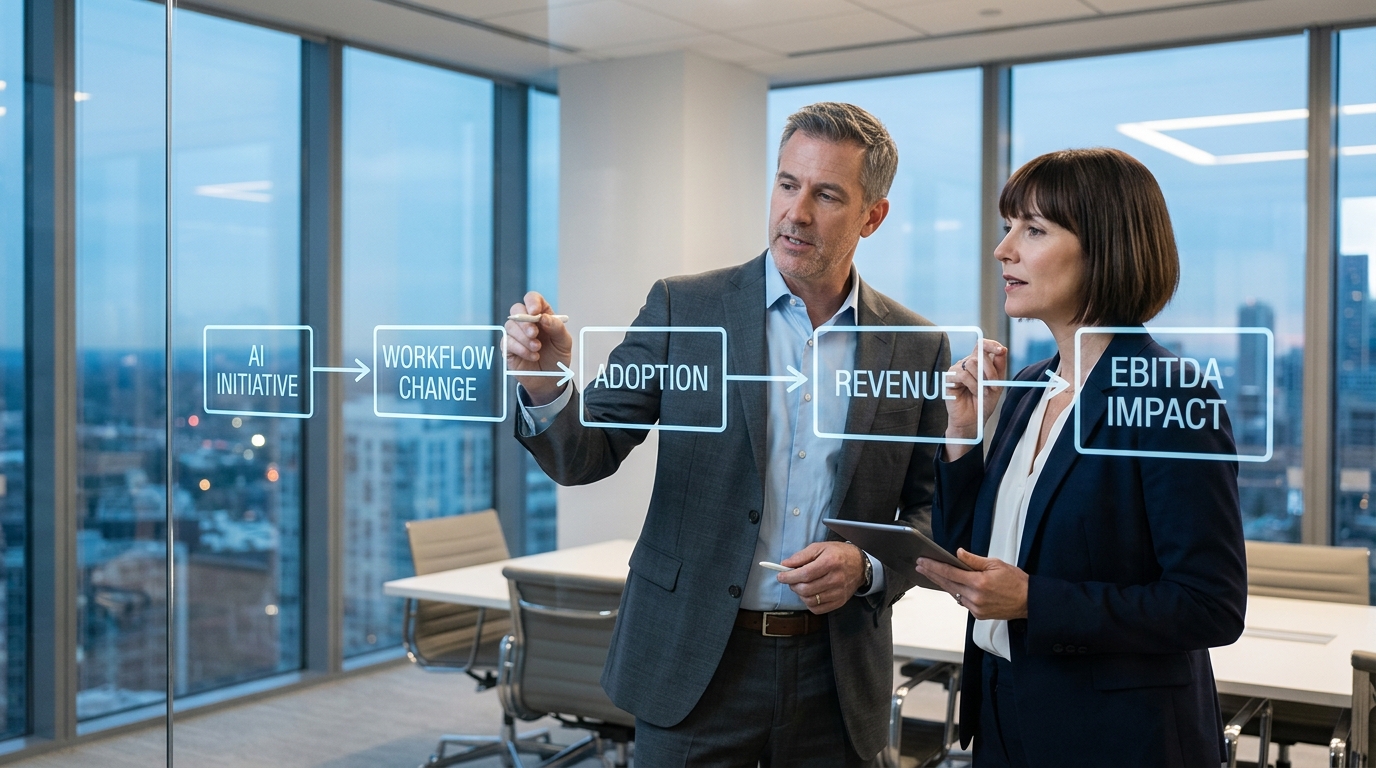
To measure AI ROI accurately, executive teams must abandon activity metrics and trace a strict causal chain: AI initiative to workflow change, workflow change to sustained adoption, adoption to a measurable operating metric, operating metric to a revenue or cost line, and ultimately to audited cash or EBITDA impact. If an artificial intelligence deployment does not alter an operating baseline and show up in financial statements, it has delivered zero return on investment.
The enterprise landscape has shifted decisively from speculative experimentation to financial accountability. According to the industry research Global Survey on the state of AI, 37% of organizations attribute at least some EBIT impact to AI use, but a mere 6% qualify as high performers who attribute 5% or more of EBIT to AI. Meanwhile, research from MIT's NANDA initiative indicates that roughly 95% of enterprise generative AI pilots fail to generate measurable P&L impact.
The root cause of this failure is a widespread confusion between operational activity and financial return. Hours saved, tokens consumed, and automated task counts do not constitute ROI. A software engineer generating code 20% faster or an analyst summarizing documents in minutes creates no financial value unless the organization translates that freed capacity into reduced external agency spend, headcount avoidance, or expanded commercial throughput.
- Activity metrics such as prompt volume or login frequency reflect software utilization, not business value.
- Productivity gains must link directly to structural line-item changes in general and administrative (G&A), research and development (R&D), or cost of goods sold (COGS).
- Demonstrating true EBITDA creation requires validating every link in the causal chain before attributing financial outcomes to AI.
The AI ROI framework: from initiative to cash
Bridging the gap between technical deployment and audited balance sheets requires a disciplined AI ROI framework. Every capital allocation toward machine learning or agentic workflows must be underwritten as an operational transformation project rather than an experimental IT license.
In industry research's 2026 AI Radar survey, 82% of chief executive officers expressed optimism about AI return on investment, yet only 6% of enterprises currently achieve meaningful financial value in reduced costs or expanded revenue. Closing this gap requires verifying three distinct operational conditions:
- Workflow reconfiguration: The underlying business process must be re-architected rather than simply overlaid with software. Intermediate approval gates, redundant reviews, and manual handoffs must be eliminated.
- Sustained workflow penetration: Adoption must be measured through active daily workflow completion rates rather than license seat activation.
- Operating metric movement: Concrete baseline key performance indicators (such as cycle time, conversion rate, or error rates) must register statistically significant variance against a control group.
Furthermore, CFOs must distinguish between EBITDA impact, cash impact, and accounting-only impact. Capitalizing internal software development costs may temporarily flatter reported operating profit while obscuring cash burn from ongoing API inference charges. A robust AI business case separates one-time productivity gains from recurring cash savings, establishing clear guardrails for sustainable value creation.
Revenue uplift: where AI moves the top line
While cost reduction dominates early automation discussions, revenue expansion represents the highest-leverage application of enterprise AI. Empirical research from industry research demonstrates that future-built companies achieve five times the revenue increases and three times the cost reductions from AI that other companies get, proving that financial returns concentrate heavily among disciplined operators.
High-quality revenue levers and attribution discipline
To establish credible revenue attribution, commercial leaders must isolate AI contributions to specific sales and pricing mechanisms:
- Conversion and win-rate improvement: Deploying AI to synthesize customer discovery notes, identify competitive risks, and tailor commercial proposals increases opportunity conversion.
- Cross-sell and customer expansion: Machine learning models analyzing telemetry and historical purchasing data identify high-probability expansion opportunities, increasing net revenue retention (NRR).
- Dynamic pricing and discounting discipline: Predictive models evaluating customer willingness to pay and contract terms protect gross margins by eliminating unapproved sales concessions.
Demand a causal operating metric before crediting top-line expansion to an AI transformation ROI model. If overall sales increase while pipeline conversion rates, average deal size, and lead cycle times remain flat, top-line growth stems from market tailwinds or headcount additions rather than software-driven leverage.
Productivity to EBITDA: the causality trap
The most common failure mode in AI business cases is the productivity-to-EBITDA causality trap. Executive teams frequently assume that reducing the time required for a task automatically lowers payroll expenses or increases margin. In practice, efficiency gains get reabsorbed into routine operational slack unless leadership enforces explicit structural changes.
industry research survey data indicates that while 32% of executives anticipated workforce reductions due to AI, only 14% of organizations reported an actual net decline in workforce over the subsequent year. To turn time saved into audited financial return, finance leaders must select one of four honest labor mechanisms:
- Headcount avoidance via unfilled attrition: Maintaining flat headcount while overall corporate transaction volume or customer count expands.
- Targeted capacity redeployment: Formally reallocating freed labor hours to revenue-generating or billable activities with trackable output quotas.
- Direct headcount reduction: Restructuring operational teams and eliminating organizational layers when end-to-end automation replaces manual workflows.
- Third-party contractor and agency reduction: Terminating outsourced service contracts, paralegal vendors, or external marketing agencies as internal software handles the volume.
Unless a management team establishes a measurable reduction in vendor invoices or an explicit reallocation of payroll hours, projected labor savings remain purely theoretical. Investment professionals implementing a structured productivity playbook evaluate whether capacity gains result in audited margin expansion or uncaptured operational slack.
The full cost side: models, inference and implementation
A comprehensive AI ROI calculation requires fully accounting for total cost of ownership. Many early financial models fail because they account only for baseline software licenses, ignoring ongoing operational compute costs and enterprise integration overhead.
Inference economics and ongoing operational expenses
Operating expenses associated with frontier models and agentic workflows are not negligible. industry research reports that about 20% of organizations find their AI usage constrained by AI-related operating costs, including token consumption and compute overhead. For complex reasoning workflows involving multi-agent architectures, inference costs scale directly with transaction volume, eroding gross margins unless carefully architected through infrastructure cost due diligence.
Implementation friction and realistic payback horizons
Enterprise AI deployments incur substantial upfront and recurring non-software expenses:
- Data pipeline engineering and retrieval-augmented generation (RAG) infrastructure.
- Security reviews, SOC 2 compliance verification, and data leakage safeguards.
- Change management, workflow retraining, and line-manager enablement.
- Continuous model monitoring, prompt maintenance, and evaluation testing.
According to Deloitte's 2025 survey of 1,854 enterprise executives across Europe and the Middle East, achieving satisfactory ROI on a typical AI use case takes two to four years, significantly longer than the standard 7 to 12 month payback period expected for conventional enterprise software. Only 6% of organizations achieve payback within 12 months. Boards and finance teams must calibrate their capital expectations to multi-year payback horizons.
The AI ROI table: metrics, financial lines and failure modes
Evaluating enterprise AI initiatives requires linking operational leading indicators directly to financial line items. The table below outlines the core initiative archetypes, their corresponding financial mechanics, standard failure modes, and the audit-grade evidence executives should demand.
| AI Initiative Type | Operating Metric | P&L Financial Line | Typical Failure Mode | Evidence to Demand |
|---|---|---|---|---|
| Customer-Facing Revenue AI | Lead conversion rate, proposal win rate, sales cycle duration | Top-line Revenue / Gross Margin | Attribution inflation; gains driven by market volume rather than software | A/B test win-rate variance against control reps; CRM pipeline velocity data |
| Back-Office & Process Automation | Invoice processing time, error rate, straight-through processing % | G&A Operating Expense / COGS | Efficiency reabsorbed; staff perform low-value busywork with freed hours | Eliminated BPO contractor invoices; verified reduction in overtime or headcount |
| Knowledge & Content Workflows | Deliverable throughput per FTE, research turnaround time | Operating Expense / Marketing Spend | Output bloat; higher content volume without performance uplift | Direct reduction in external agency retainers; verified deliverable volume per FTE |
| Software Engineering Tooling | Pull request cycle time, sprint velocity, defect escape rate | R&D Expense / COGS | Code volume increase without architectural quality or software savings | Reduced contractor engineering spend; software build-vs-buy cost offset |
| Decision Support & Analytics | Forecast variance, inventory scrap rate, working capital turnover | COGS / Working Capital / Gross Margin | Model outputs ignored by line management; static decision processes | Audited reduction in forecast error margin; documented inventory carrying cost reduction |
By applying this structured matrix, corporate development teams and CFOs can systematically identify whether an AI program delivers verifiable financial performance or merely operational activity.
How CFOs and investors should pressure-test the AI case
To safeguard capital, CFOs, corporate investment leads, and private equity sponsors must subject AI claims in business plans and portfolio budgets to rigorous scrutiny. For investment professionals evaluating platform capabilities, maintaining repeatable diligence systems is essential to separate defensible operational moats from commoditized software wrappers.
Structuring the institutional AI business case
CFOs must require every sponsor of an internal AI project to present a business case built on strict counterfactual logic:
- Establish a fixed historical baseline for unit labor hours and third-party vendor costs before deployment.
- Model conservative sensitivity curves on employee adoption rates and token inference costs.
- Separate capitalized development expenditures from ongoing cash operating expenses.
- Tie project milestone funding directly to verified reductions in external spend or confirmed headcount adjustments.
Investor due diligence: interrogating the business plan
When evaluating an M&A target claiming AI-driven margin expansion or software differentiation, deal teams should reject aggregate metrics like user counts or generic productivity claims. Due diligence teams must inspect workflow-level telemetry, cohort retention, and unit economics per processed transaction.
This is where specialized diligence infrastructure proves essential. PLAUSITY provides evidence-backed AI Impact DD and Value Creation DD, enabling investment professionals and finance leaders to stress-test technical claims against audited evidence. Using core capabilities such as the Data Room Ingestion engine, Risk Radar, and AI-Analysis Engine, Plausity cross-references operational data and documentation to verify whether AI initiatives translate into structural P&L advantages. Finance and deal teams who want to apply this evidence-based approach to their own AI initiatives or acquisition targets can request a demonstration of the workflow through the AI Impact DD page.
How Plausity accelerates this workflow
Plausity is an AI-native due diligence and deal intelligence workspace that helps M&A advisory firms, VC and PE funds, corporate development teams and investment-banking teams structure evidence, findings and questions across a data room. Plausity supports evidence extraction, source grounding, findings management and IC preparation — it does not replace human analysts, advisers or investment professionals, does not provide legal, tax, audit, regulatory or investment advice, and does not make autonomous investment decisions. All findings require human review. Built for today's investment and deal teams. Trusted by >200 firms.
To explore the underlying capabilities, see the Plausity AI analysis engine, the findings and risk intelligence and evidence gap detection product pages, and the IC memo product page. For team-level workflows, see how VC and PE funds and M&A advisory firms use Plausity across live deals, and how AI Impact due diligence and value creation workstreams support the analysis.