What kind of AI acquisition are you actually making?
How should a company decide what kind of AI acquisition it is actually making, and diligence it accordingly? The direct answer: before any diligence workstream opens, classify the deal as one of four archetypes, a capability buy, a product expansion, a platform assembly, or an infrastructure and ecosystem position, and then match the evidence, the risk register and the integration plan to that classification. Misclassification is the root cause of failed AI deals: a team bought as a capability but integrated as a product line loses the people it paid for, and a platform assembled from point solutions without a data-rights audit is a Frankenstein stack with a valuation attached. The classification is not academic. It determines which documents matter, which experts sit in the room, and what the first hundred days after closing are for.
The traditional playbook breaks because the asset perimeter no longer holds. As Deloitte puts it, the old script assumed a well-defined asset, a factory, a brand, a software platform, surrounded by a clean perimeter before diligence began. When the asset is people, code and compute contracts, scope cannot be fixed up front, talent has agency, and everything is interdependent, so the transaction perimeter is often only fully understood after signing. Diligence built for a static snapshot of a defined asset will systematically miss what an AI target actually is.
The market context sharpens the stakes. industry research's analysis of strategic majority acquisitions in the AI ecosystem finds that capability buying and product expansion together accounted for 95% of all acquisitions from January 2020 through August 2026, while platform assembly is the only motive moving materially, rising from 3% of volume in 2020 to 9% in the first part of 2026. PwC tracks global deal value on course for roughly $4tn in 2026, the strongest year since 2021, with megadeals above $5bn now representing 48% of total value, double their share two years ago. deal databases recorded $255.5bn of AI venture funding in Q1 2026 alone, surpassing the full-year 2025 total, with SpaceX's $250bn acquisition of xAI standing as the largest AI-related M&A transaction ever recorded. Capital is abundant; the discipline to classify what is being bought is not.
- Capability buy: the target is a team, a model or applied research that the buyer cannot build quickly enough internally.
- Product expansion: the target is a working AI product that slots into an existing portfolio and revenue base.
- Platform assembly: the deal combines several AI building blocks into one coherent platform, the fastest-growing deal motive in the ecosystem.
- Infrastructure and ecosystem position: the transaction secures data, distribution, compute or integration positions, where the largest deals now concentrate.
Capability buy: talent, models, applied research
Each archetype carries a different strategic objective, demands different evidence, fails in different ways and creates value through a different mechanism. The framework table below is the article's working tool: locate the deal in one row before designing the diligence plan, and resist the temptation to run the same checklist across all four. industry research's maturity arc is useful here as well: capability buying corresponds to Phase 1, product expansion to Phase 2, and platform assembly to Phase 3, and the mix of motives across the ecosystem tells an acquirer which stage a given segment has reached.
In a capability buy, the objective is know-how the buyer cannot build quickly enough, and targets are often small, pre-revenue and valued for what they can do rather than what they earn. The evidence that matters is the key-person map, publication and model lineage, retention economics, IP assignment records and incentive structures; the key risk is that talent walks before or shortly after close, or that IP turns out to be personal rather than institutional. Value is created through speed-to-retention: operational autonomy, incentives and a credible research mandate from day one.
| Acquisition type | Strategic objective | Evidence required in diligence | Key diligence risk | Integration challenge |
|---|---|---|---|---|
| Capability buy (talent, models, applied research) | Acquire know-how the buyer cannot build quickly enough; targets often pre-revenue and valued for what they can do | Key-person map, publication and model lineage, retention economics, IP assignment records, non-compete and incentive structures | Talent walks before or shortly after close; IP is personal rather than institutional | Speed-to-retention: operational autonomy, incentives and a credible research mandate from day one |
| Product expansion (working AI product into an existing portfolio) | Fill a product-line gap and move from point solutions to a more complete proposition | Revenue quality, cohort retention, customer concentration, churn drivers, pricing power, roadmap credibility | Revenue is concentrated in customers the buyer cannot retain post-close | Commercial integration: pricing, sales coverage and support migration without breaking live customer commitments |
| Platform assembly (combining AI building blocks into a coherent platform) | Enter adjacencies, tie products into an integrated platform, buy volume, distribution or reach; the fastest-growing motive at 9% of volume | Architecture maps across targets, data-model compatibility, licence chains for every training corpus, overlapping vendor contracts | Fragmented components that never cohere; duplicated vendor spend and conflicting data schemas | Technical unification: one data layer, one identity model, one roadmap, agreed within the first two quarters |
| Infrastructure / ecosystem position (data, distribution, compute, integrations) | Secure a structural position in the AI stack; the largest deals concentrate here, including SpaceX's $250bn acquisition of xAI | Contract assignability for compute and data commitments, regulatory and antitrust posture, capital-expenditure obligations, ecosystem dependency map | Regulatory block or unpriced infrastructure commitments that sit inside the acquired perimeter | Operating-model integration at scale: governance, capital discipline and ecosystem orchestration across jurisdictions |
Two observations keep the table honest. First, the archetypes are not mutually exclusive: a single transaction can be a capability buy with a product-expansion tail, and industry research notes explicitly that the phases are neither rigid nor sequential. Second, the archetype determines the buyer, not just the diligence. Ecosystem companies buying other ecosystem companies still represent a minority of AI-target transactions, with buyers outside the ecosystem outnumbering those inside roughly two to one, which means most acquirers are classifying a deal for the first time, not the fifth.
Product expansion: adding a working AI product
Talent retention and management continuity
In a capability buy, talent is not one diligence workstream among several; it is the asset. Everything else, the models, the publications, the customer relationships, is downstream of a few dozen people deciding to stay. Deloitte is blunt about the asymmetry: unlike a plant or a patent portfolio, talent can walk out the door, and speed-to-retention is not a nice-to-have but existential, because deals that take months to close risk losing the very capability they were designed to secure.
The structure of the deal should follow from that reality. Deloitte identifies three dominant structures that transfer teams without a full entity transfer: acquihires that bring in critical research and engineering teams while the original company continues operating independently; non-exclusive IP licensing that gives buyers immediate access to differentiated technology without a change-of-control transaction; and strategic partnerships, often built around minority investments, compute commitments and commercial distribution, that align incentives while preserving operational independence. Each structure trades exclusivity for speed, and each demands that the buyer answer a harder question than the purchase agreement usually contemplates: what, exactly, is being retained, and for how long?
Diligence evidence should be specific and documentary, not impressionistic. The following items separate a team that will stay from a team that is already drafting resignation letters:
- Key-person dependency map: who owns the model architecture, the training pipeline and the customer relationships, and what happens if each leaves.
- Retention economics: vesting schedules, acceleration clauses, unvested equity at close, and the delta between the target's compensation and the acquirer's bands for equivalent roles.
- Management incentives: rollover equity, earnouts tied to team retention rather than revenue alone, and the credibility of the research mandate offered post-close.
- Post-close operating autonomy: reporting lines, publication and open-source policies, compute budgets, and whether the founder-CEO stays or is replaced by a corporate executive.
- Culture and continuity signals: attrition in the twelve months before signing, counteroffers already made, and whether the team has been through an acquisition before.
Management continuity deserves equal weight in product and platform deals, where the acquired leadership usually understands the technology better than the buyer does. The integration plan should name, before signing, which executives stay, which decisions they own, and which corporate processes they are exempt from. Ambiguity on any of these points is read, correctly, as a signal that the buyer values the asset but not the people.
Proprietary data and data rights
Two asset classes determine whether an AI target owns anything durable: proprietary data, and the right to operate the models trained on it. Both are routinely overvalued because both are hard to audit under deal timelines. The diligence question for data is provenance and the licence chain: where did every training corpus come from, under what licence, and do those rights survive a change of control? A dataset scraped under terms that terminate on acquisition, or licensed for research use only, converts the target's most valuable asset into a contingent liability the day the deal closes.
Third-party model dependency and vendor lock-in
The second asset class is the dependency stack. Most AI products are thin layers over third-party foundation models accessed through APIs, and the diligence question is what happens to unit economics if inference costs rise, terms change, or a provider restricts access. Deloitte's observation that the acquired asset spans people, proprietary code and cloud compute contracts across multiple jurisdictions applies directly here: compute commitments, GPU reservations and minimum-spend clauses are part of the perimeter being acquired, whether or not they appear on the balance sheet. An acquirer that prices the equity but not the compute contract has mispriced the deal.
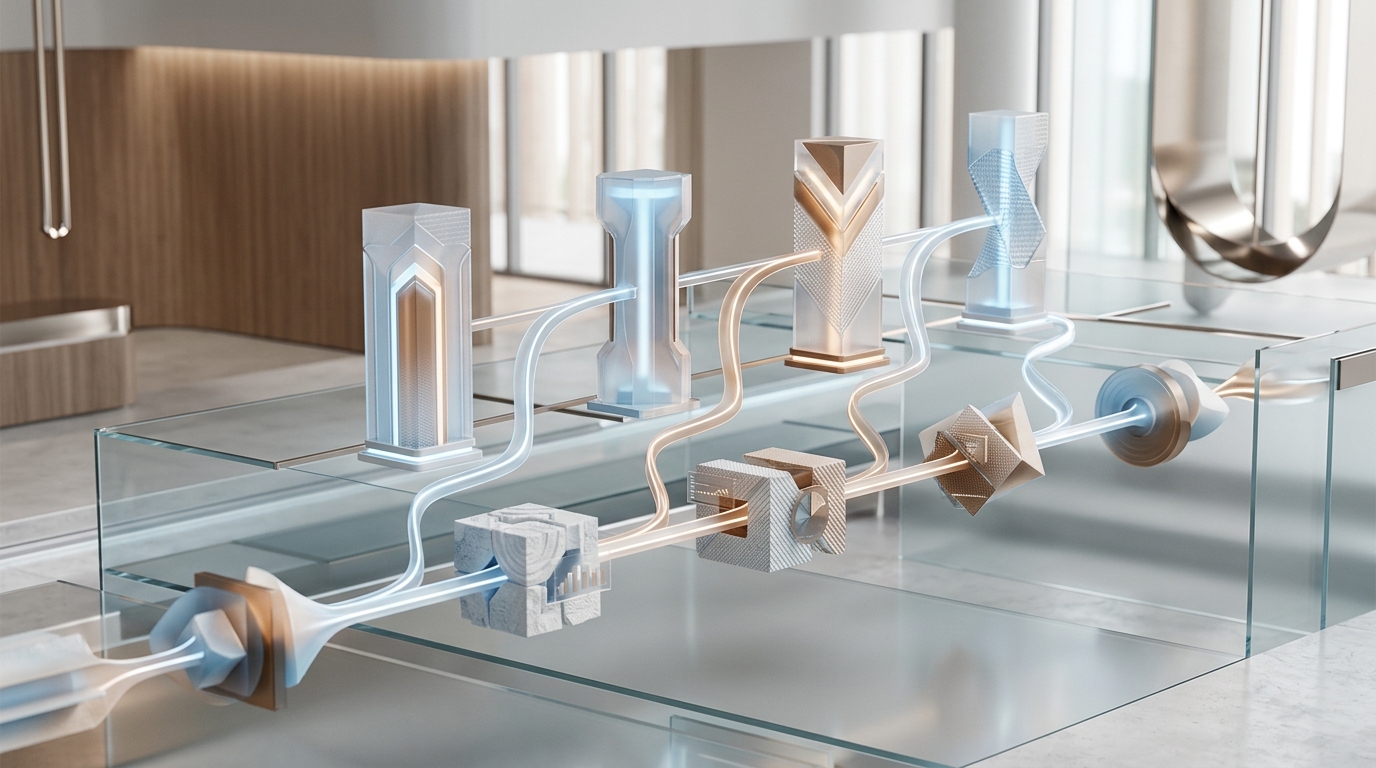
The stack diagram above is a useful audit template because dependency compounds upward. A proprietary dataset with a broken licence chain poisons the fine-tunes built on it; a fine-tune locked to a single provider's API converts every downstream application into a hostage of that provider's pricing. The evidence to demand includes the licence chain for each training corpus, the model cards and evaluation results for each fine-tune, the API dependency map with current unit economics per provider, the fallback plan if a primary provider changes terms, and the assignability of every compute contract under a change of control. Where the target claims a data moat, test it: how reproducible is the corpus from public sources, and how fresh is it?
IP, indemnities and regulatory posture
The legal tests decide whether the deal creates value on a realistic timeline, and they begin with ownership. Model weights, training code, evaluation harnesses and research output each carry their own chain of title, and in capability buys the chain often runs through named individuals whose assignment agreements were signed years ago under different employment terms. Deloitte recommends building a defensibility package at speed: thorough, auditable records of IP at close, designed for the post-close inquiries that inevitably follow access-driven transactions, because significant consideration may be held back pending demonstrated completeness of transfer.
Indemnities follow the same logic. Training-data liability, meaning copyright and licence claims over the corpora, and output liability, meaning harm caused by model outputs in production, are the two exposures most often under-specified in purchase agreements. The diligence file should quantify both: which corpora carry documented licences, which are defensible under fair-use or equivalent doctrines in the relevant jurisdictions, and what the target's contractual position is with its own customers on output claims. Regulatory posture completes the picture. The EU AI Act imposes obligations that scale with model capability and use case, and an acquirer inheriting a deployed system inherits its compliance file, or its absence.
Commercial fit and time-to-value
The market is already pricing this selectively. PwC's analysis of the 100 largest corporate M&A transactions finds that AI's role has become more selective: in 2025 approximately one-third of the deals analysed cited AI as part of the strategic rationale, but in the first half of 2026 that fell to 17%, with references concentrated in sectors closest to the AI buildout. Buyers, in PwC's words, are becoming more disciplined about where AI creates durable demand and where a partnership or minority investment may be a better route than full ownership. The commercial test that ties the legal file together is Deloitte's operational readiness question: can the buyer run the acquired capability on Day 1 and improve it by Day 30, with the people, IP, systems, data and infrastructure capacity mapped to specific timelines and business outcomes? A deal that cannot answer that question has a value-creation thesis, not a value-creation plan.
Common failure patterns
The failure patterns recur with striking consistency, and nearly all of them trace back to the classification error this framework is designed to prevent. Deloitte's account of why the traditional playbook breaks maps directly onto five recurring failures: deals misclassified at the outset, so the diligence examines the wrong asset; post-close talent attrition, because speed-to-retention was treated as an HR detail rather than an existential constraint; thin data rights, where the licence chain does not survive the change of control; unpriced model dependency, where inference costs and vendor terms sit outside the deal model; and stalled integration between signing and value realization, which forfeits the speed advantage that justified the structure in the first place.
Evidence checklist for AI M&A
The countermeasure is a compact evidence checklist, organised by archetype, that the deal team agrees on before the letter of intent is signed. Each row names the proof that must exist in the data room, not the assertion that should be true in the pitch:
- Team: key-person map, retention economics, incentive structures and post-close operating autonomy, weighted heaviest for capability buys.
- IP: chain of title for weights, code and research output; assignment agreements for named individuals; indemnity coverage for training-data and output liability.
- Data: licence chain for every training corpus, change-of-control survival, reproducibility of the claimed data moat, and freshness of the corpus.
- Infrastructure: compute contracts and their assignability, API dependency map with unit economics per provider, and the fallback plan if terms change.
- Commercial: revenue quality and cohort retention for product deals; architecture compatibility and vendor-overlap analysis for platform deals; regulatory and antitrust posture for ecosystem positions.
Leading acquirers are increasingly running this checklist with AI in the diligence itself. industry analysis's survey of more than 300 M&A executives found that adoption of AI tools more than doubled in 2025, with 45% of respondents now relying on the technology, and about one-third of dealmakers deploying AI systematically or redesigning M&A processes around it. industry research's survey work points the same direction: respondents using gen AI in their M&A activities report an average cost reduction of roughly 20%. The tooling does not replace the classification judgment, but it changes what a deal team can verify in the time a competitive process allows.
Running AI diligence at deal speed
Operationalising this playbook under compressed timelines is the practical constraint on everything above. A four-archetype evidence file is easy to specify and hard to produce when the data room opens three weeks before bids are due and contains thousands of contracts, model documentation pages and financial models in mixed formats. This is where an AI-native due diligence platform changes the economics of the work: Data Room Ingestion scans VDR documents within minutes, the AI-Analysis Engine reads, cross-references and reasons over thousands of documents to generate analysis, Risk Radar surfaces findings by materiality, financial impact and deal relevance, the Collaboration Hub coordinates workstreams in real time, and Report Builder drafts investor-ready deliverables with full source traceability. PwC describes the same shift at market level: AI is accelerating diligence, valuation and investment committee preparation, with AI-enabled data rooms and deal platforms already analysing and summarising large volumes of documents and surfacing potential risks.
Plausity's services map directly onto the four archetypes. AI Impact DD tests how AI affects a target's business-model durability and competitive position. Tech DD audits the dependency stack, from data rights and model lineage to compute contracts. Commercial DD tests revenue quality, retention and time-to-value for product and platform deals. AI for M&A equips the deal team itself with AI-native workflows, and Value Creation DD converts the diligence file into a post-close plan with named levers and timelines. The through-line is archetype-specific evidence, produced at deal speed, so the classification decision is tested against documents rather than assertions. Teams running a live AI transaction can arrange a demo with Plausity to see the archetype-specific evidence file assembled on their own deal documents.
Sources
Platform assembly: combining AI building blocks
Platform assembly deals enter adjacencies, tie products into an integrated platform, and buy volume, distribution or reach; this is the fastest-growing motive, rising from 3% to 9% of AI acquisition volume since 2020. The evidence required is architecture maps across targets, data-model compatibility, licence chains for every training corpus and overlapping vendor contracts; the key risk is fragmented components that never cohere, with duplicated vendor spend and conflicting data schemas. Value is created through technical unification: one data layer, one identity model and one roadmap, agreed within the first two quarters.
Infrastructure and ecosystem positioning
Infrastructure and ecosystem deals secure a structural position in the AI stack, in data, distribution, compute or integrations, and the largest transactions concentrate here. The evidence required is contract assignability for compute and data commitments, regulatory and antitrust posture, capital-expenditure obligations and an ecosystem dependency map; the key risk is a regulatory block or unpriced infrastructure commitments sitting inside the acquired perimeter. Value is created through operating-model integration at scale: governance, capital discipline and ecosystem orchestration across jurisdictions.
A product expansion fills a product-line gap and moves the buyer from point solutions to a more complete proposition. The diligence evidence shifts to revenue quality, cohort retention, customer concentration, churn drivers, pricing power and roadmap credibility; the key risk is revenue concentrated in customers the buyer cannot retain post-close. Value is created through commercial integration: pricing, sales coverage and support migration without breaking live customer commitments.
How Plausity accelerates this workflow
Plausity is an AI-native due diligence and deal intelligence workspace that helps M&A advisory firms, VC and PE funds, corporate development teams and investment-banking teams structure evidence, findings and questions across a data room. Plausity supports evidence extraction, source grounding, findings management and IC preparation — it does not replace human analysts, advisers or investment professionals, does not provide legal, tax, audit, regulatory or investment advice, and does not make autonomous investment decisions. All findings require human review. Built for today's investment and deal teams. Trusted by >200 firms.
To explore the underlying capabilities, see the Plausity AI analysis engine, findings and risk intelligence and evidence gap detection product pages, plus the IC memo and AI Q&A Assistant product pages. For team-level workflows, see how VC and PE funds and M&A advisory firms use Plausity across live deals, and how AI Impact due diligence, value creation, Tech DD and Commercial DD workstreams support the analysis.